Employee ownership is how American workers build generational wealth.

LSI research examines the federal and state policy levers, business succession pathways, and capital structures most likely to scale employee ownership, and to route more retiring American businesses into the hands of the workers who built them.

Our View

Employee ownership builds economic mobility for workers across the United States.

Employee ownership is a proven strategy to retain domestic ownership and investment while building generational wealth for American workers. For most of American history, a durable route from worker to wealth-builder was to start a business. For families without inherited capital, that route has narrowed. Employee ownership offers another: a share of the company you already work for, paid for out of the company's own earnings, and built over decades of service.

The policy rationale first entered federal law in 1974, through the Employee Retirement Income Security Act, whose ESOP provisions were championed by Senator Russell Long of Louisiana.1 It has drawn co-sponsorship from both parties in every subsequent decade. Most recently, Senators Chris Van Hollen and Jerry Moran introduced the American Ownership and Resilience Act in 2025, alongside Representatives Blake Moore and Lori Trahan, to begin to close the capital gap that limits how quickly employee ownership can expand.2

The outcomes are well-documented. Employee-owned companies generate roughly 2.5 times more retirement wealth for workers than conventionally-owned peers,3 lay off fewer workers in downturns, grow faster, retain more local jobs through ownership transitions, and account for a disproportionate share of the American manufacturing base. The benefits are most pronounced for low- and moderate-income workers, who are otherwise least likely to hold capital assets of any kind.

What has not kept pace is scale. Roughly three million American workers currently hold meaningful ownership stakes in approximately six thousand employee-owned companies.4 Tax incentives for selling owners exist but are unevenly applied. State statutes vary widely. And the capital stack required to finance an employee-ownership transition remains narrow, relying on bank leverage and long-term seller financing that many retiring owners are unwilling to accept.

LSI's employee ownership portfolio works on three fronts. Federal and state policy research identifies the tax, regulatory, and statutory reforms most likely to scale ownership. Accessible data tools make business succession opportunities legible to lawmakers, retiring owners, and investors at the district and state scale. LSI translates the findings into options that lawmakers of either party, community organizations, investors, and other mission-driven actors can act on.
Research Priorities

Business succession

Approximately 2.9 million American businesses are expected to change hands over the next decade.5 Research on the policy, financing, and awareness levers that can route more of them into employee ownership rather than out-of-market sales, closures, or rollups.

The policy architecture of ownership

The federal and state statutes, tax code provisions, and Department of Labor regulations that govern how and whether employee ownership can scale. Research on the reforms most likely to unlock the next generation of employee owners without new federal spending.

Financing employee ownership

The capital structures that make employee-ownership transitions possible. Research on the bank leverage, seller financing, and institutional capital vehicles most likely to close the financing gap that currently limits how quickly employee ownership can expand, including the bipartisan American Ownership and Resilience Act.

Worker wealth

Empirical research on what a share of ownership does for a family over the course of a career: wages, retirement assets, job stability, and participation in company decisions.

Flagship Report

Financing the Growth of Employee Ownership: Closing the Capital Gap for ESOP Transitions

Employee ownership works. Yet every year, thousands of retiring owners sell to strategic buyers or private equity because the financing pathway for an ESOP transition is longer, more expensive, and less well understood than the alternatives. This paper proposes the federal and state financing tools needed to make employee ownership the default option for succession in the American middle market.

Library Publications

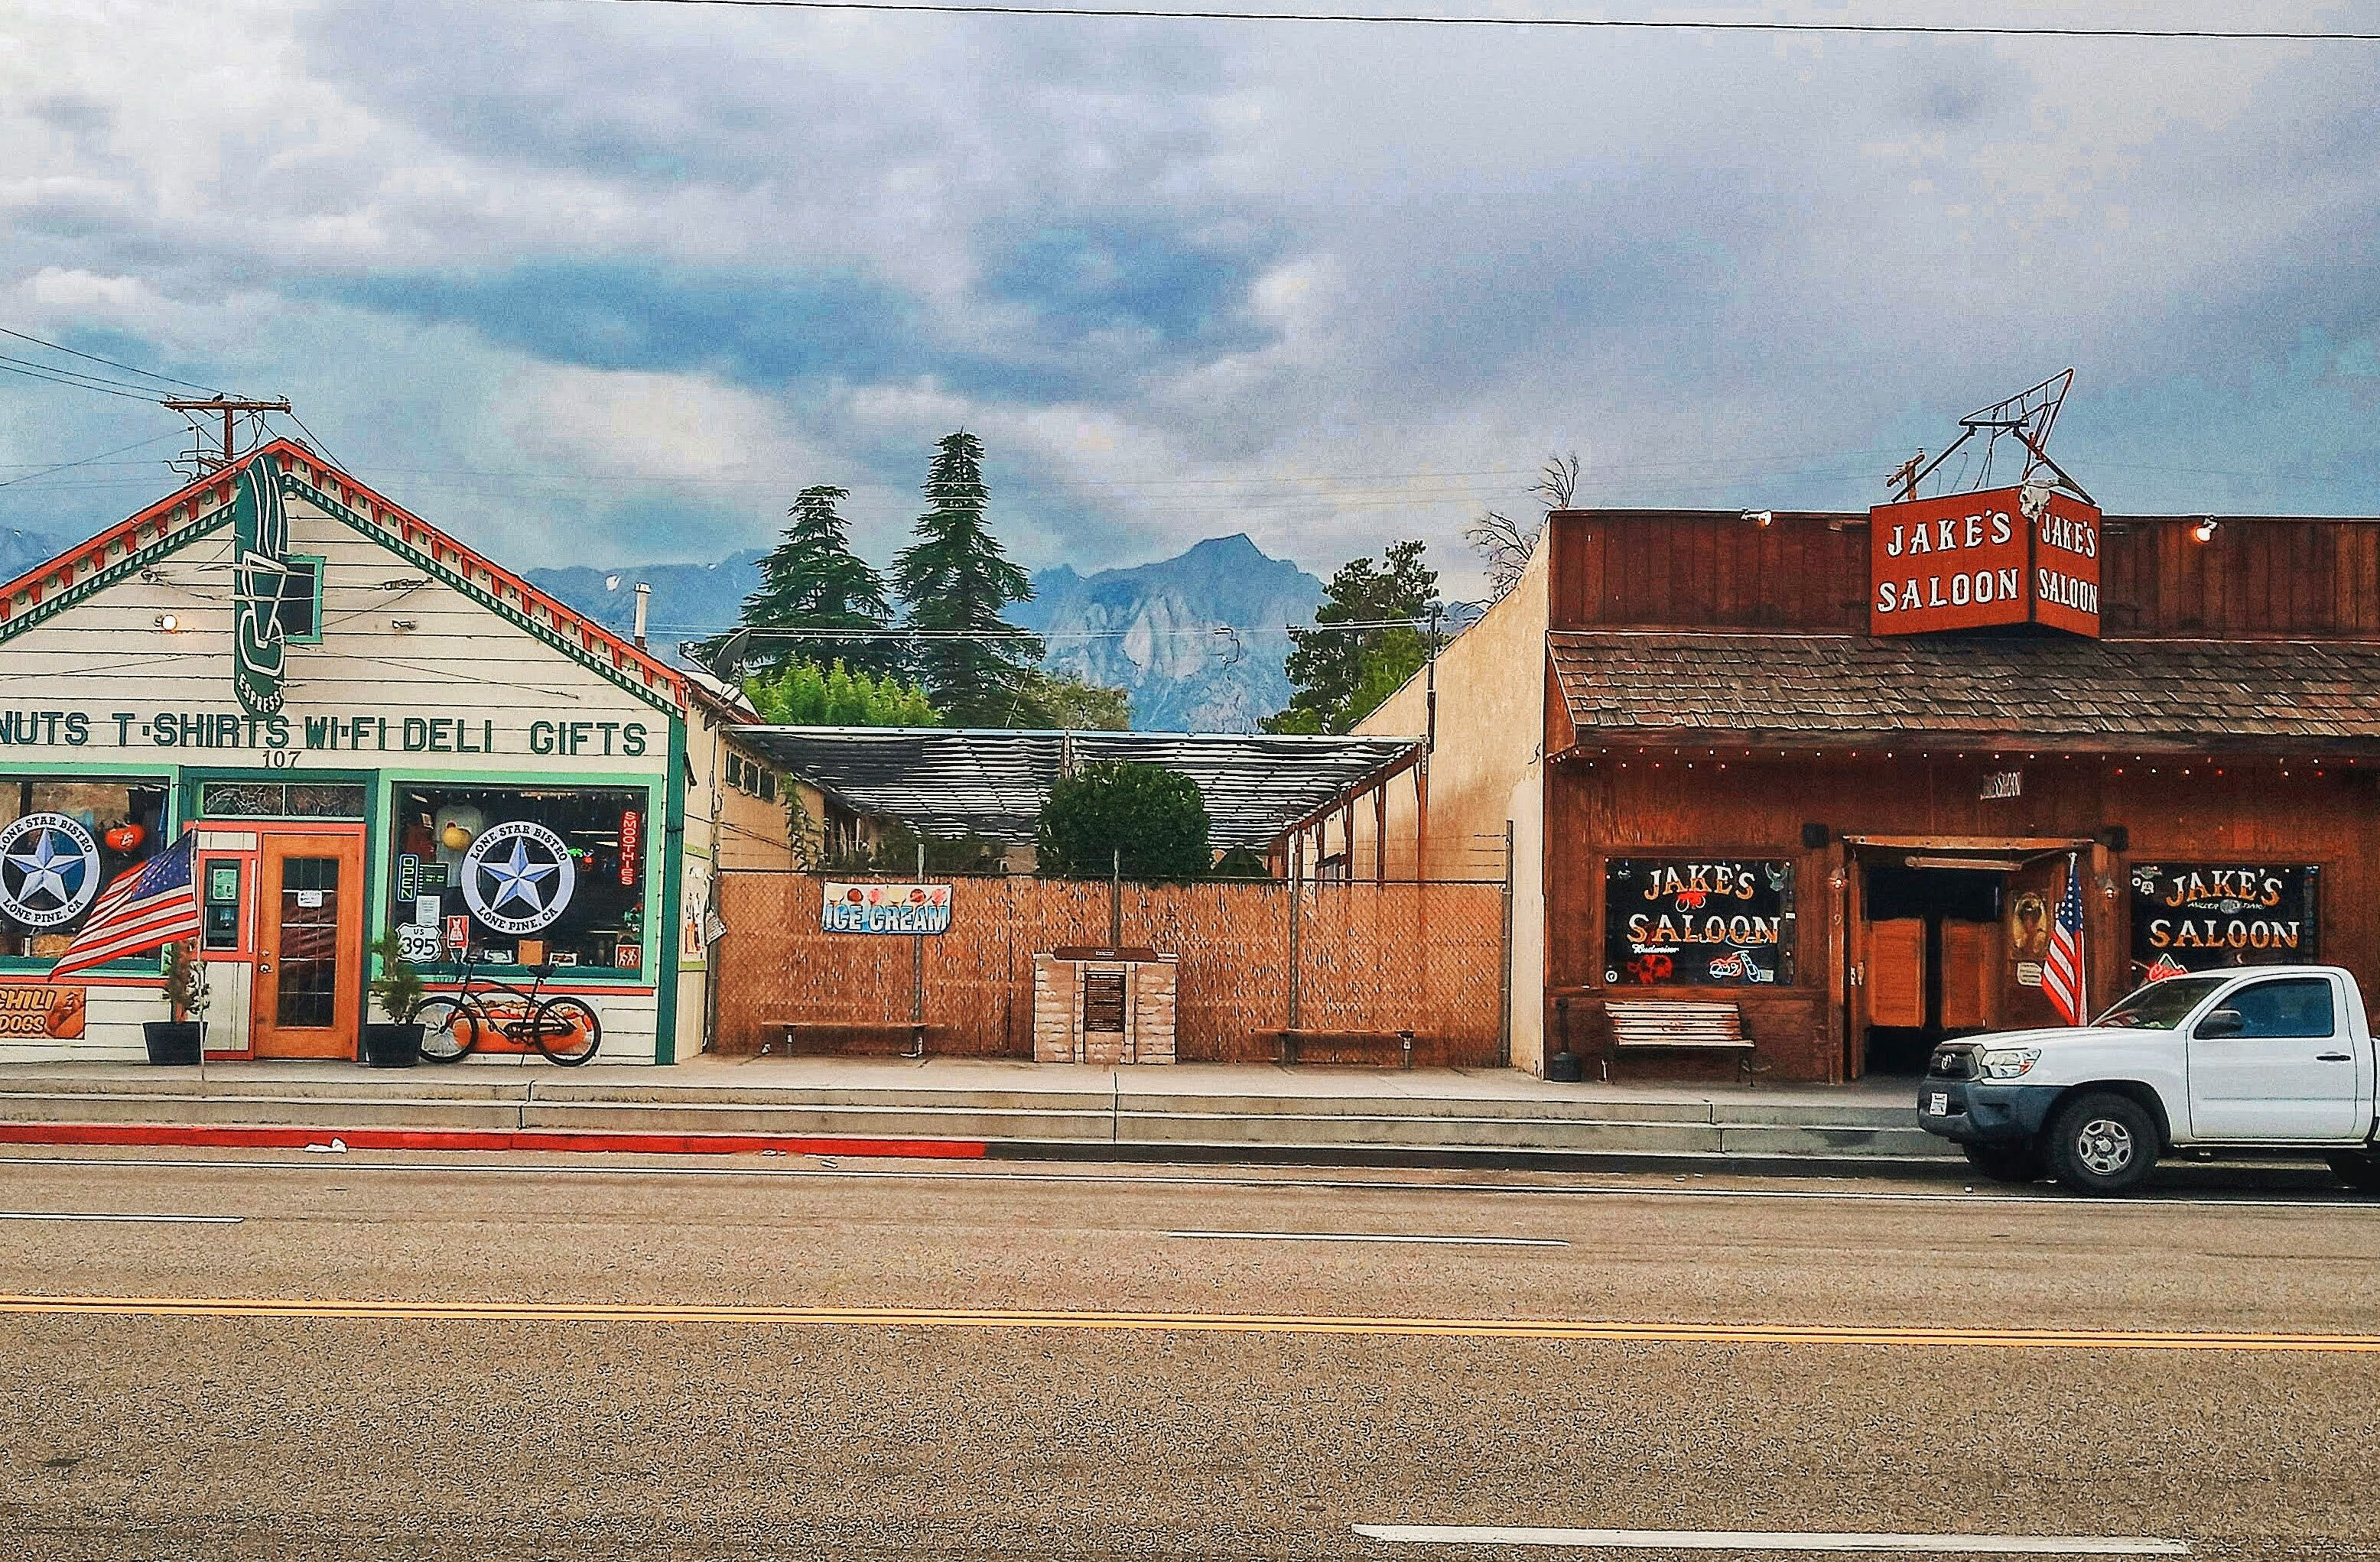
Storefronts on a rural main street

Research Brief

Rural Business Succession: The Role of Employee Ownership

A record number of U.S. business owners are approaching retirement without a clear succession plan. These challenges are especially acute in rural areas of the country, where older owners, older firms, and a limited pool of buyers can make ownership transitions harder and business closures more likely.

Read

Sources

  1. Employee Retirement Income Security Act of 1974, Pub. L. 93-406, 88 Stat. 829, signed Sept. 2, 1974. ESOP provisions at §§407(d)(6) and 408(e) were authored principally by Senator Russell B. Long (D-LA).
  2. American Ownership and Resilience Act, S.1645 / H.R.3248, 119th Congress (2025–2026). Sens. Chris Van Hollen (D-MD) and Jerry Moran (R-KS), Reps. Blake Moore (R-UT) and Lori Trahan (D-MA).
  3. National Center for Employee Ownership & Institute for the Study of Employee Ownership and Profit Sharing (Rutgers), Employee Ownership and Economic Well-Being, 2017; updated in NCEO, Employee Ownership by the Numbers, 2024.
  4. National Center for Employee Ownership, Employee Ownership by the Numbers, 2024. Figures reflect ~6,500 ESOPs covering ~14.7 million participants; "meaningful stakes" narrows to active employees at majority employee-owned firms.
  5. Project Equity, The Case for Employee Ownership, 2023; derived from Census Bureau Annual Business Survey (ABS) owner-age distributions and SBA succession research.